High-Margin Pool Finishing & Outdoor Living Platform · Southeast · $3M+ EBITDA, 20%…
GA
About this business
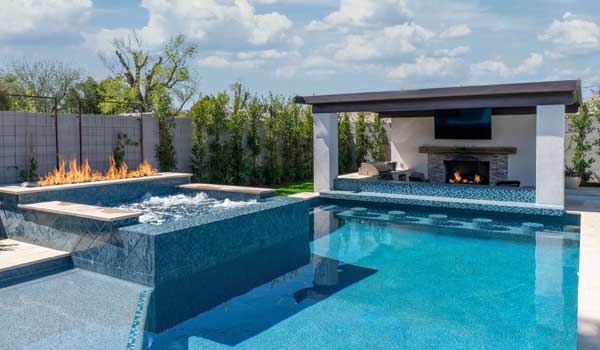
Specialty pool finishing and outdoor living platform generating approximately $16M in revenue and over $3M in adjusted EBITDA, growing at a 20% three-year CAGR. More than 90% of revenue is concentrated in pool resurfacing and renewal — a focused, recurring-demand category driven by the 7-to-10-year replacement cycle on existing pools — at approximately 19% EBITDA margins. The business serves commercial and residential clients across the Southeast U.S., earning revenue as a preferred subcontractor to regional pool builders, HOAs, and municipalities on existing-pool renewal and finishing work, complemented by higher-margin tile, deck, and hardscape enhancement projects. The company operates a scalable, crew-based model with 80+ field crews and a small W-2 office team, supported by a 30+ vehicle fleet and a multi-year institutional lease at its operations hub. Direct-from-manufacturer material purchasing — enabled by warehouse capacity expansion in late 2023 — created a structural cost advantage and drove an 11-point gross margin expansion over three years (15% to 26%). Certification with leading premium pool finishing systems secures specification-driven work and reinforces a durable competitive moat. The customer base spans 100+ active accounts built entirely through referral and reputation, with concentration in two strategic anchor builder relationships and a long tail of recurring repeat customers — zero paid marketing or outbound sales investment. The opportunity for a financial sponsor is a defensible platform in a fragmented industry where this business has consistently outperformed peers on growth, safety, and warranty performance. The Company's 20% CAGR against industry growth of approximately 0.5% reflects sustained share capture, supporting a clear roll-up thesis for buyer-driven geographic expansion. A differentiated 10-year warranty (versus 1-2 years offered by most regional competitors), pristine five-year workers' compensation loss history, and documented quality controls distinguish the Company from sub-scale operators and support pricing power. The founder pursues a partial exit and is open to 15-25% equity rollover and a 12-24 month advisory role. A layered management structure (office, estimating, and crew leadership) enables seamless transition and straightforward integration of buyer-installed leadership for regional consolidation and geographic expansion across the Southeast.
Details
| Established | 2011 |
|---|---|
| Location | Georgia |